
Mobile Friendly Tony’s View
Input to your Strategy for Adapting to Challenges
Feel free to pass on to friends and clients wanting independent economic commentary
ISSN: 2703-2825
12 November 2026
Sign up for free at www.tonyalexander.nz
Job worries drive spending plan reductions
If you’ve not read enough about the general election outcome yet and are looking forward to myself adding to the heap – get help. I’ve nothing to add beyond noting that the likely but not 100% certainty of a centre-right victory means continuation broadly of current policies but with an extra tilt towards those favoured by NZ First and ACT because of their gains in seats versus National.
I recall this period of waiting for the final outcome three years ago and how great it felt not to be bombarded by the media with endless analysis and speculation. It felt like weeks of Boxing Days.
This time around the unfortunate effect is likely to be a lengthening of the period during which businesses hold back from making important investment and hiring decisions. In fact, come November 27 many are likely to then realise the Christmas holidays are almost at hand so one may as well put things on hold until February – especially as the Coalition Agreement will take some further time to finalise. The already long period of delayed firm recovery in our economy has longer to run.
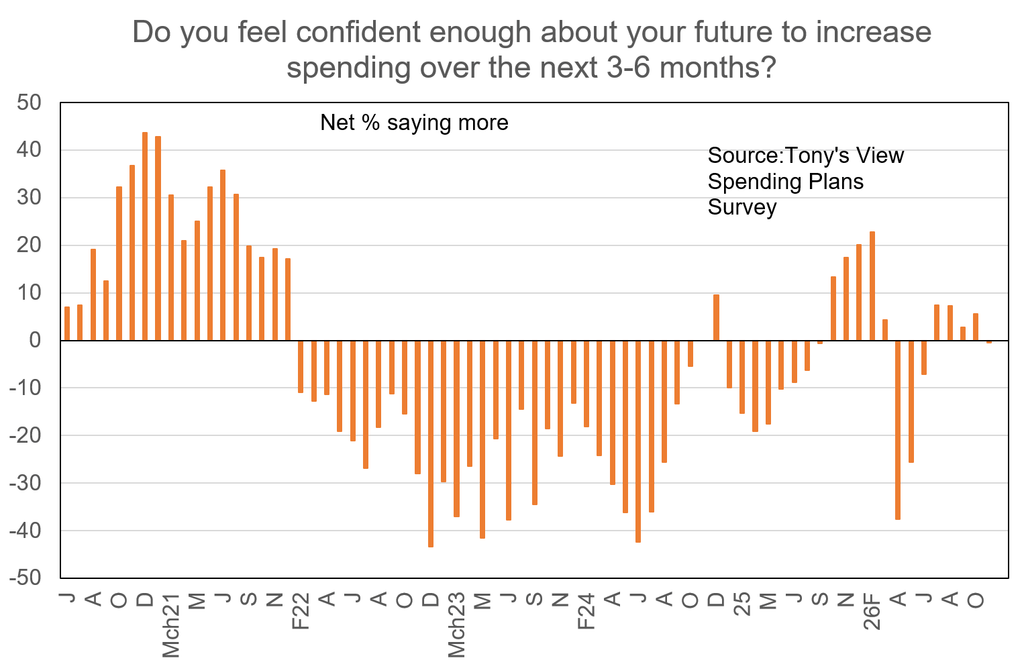
This week I am going to run through the key results from my monthly Spending Plans Survey conducted just under a week ago. The headline result is a small decline in net plans to spend more over the coming 12 months to -0.5% from +6% early last month. The outlook for retailers has got a little bit worse and if people choose to take advantage of Black Friday specials to purchase goods, then Christmas sales of the same things are likely to be weak.
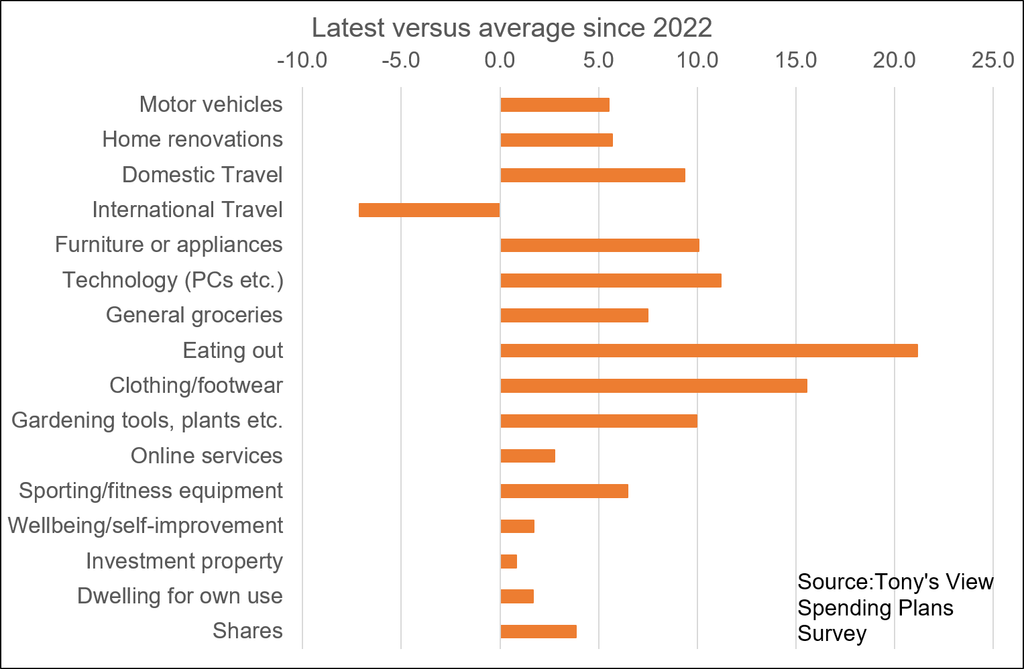
Compared with average spending plans are strongest for Eating out. The only below average reading is for International Travel.
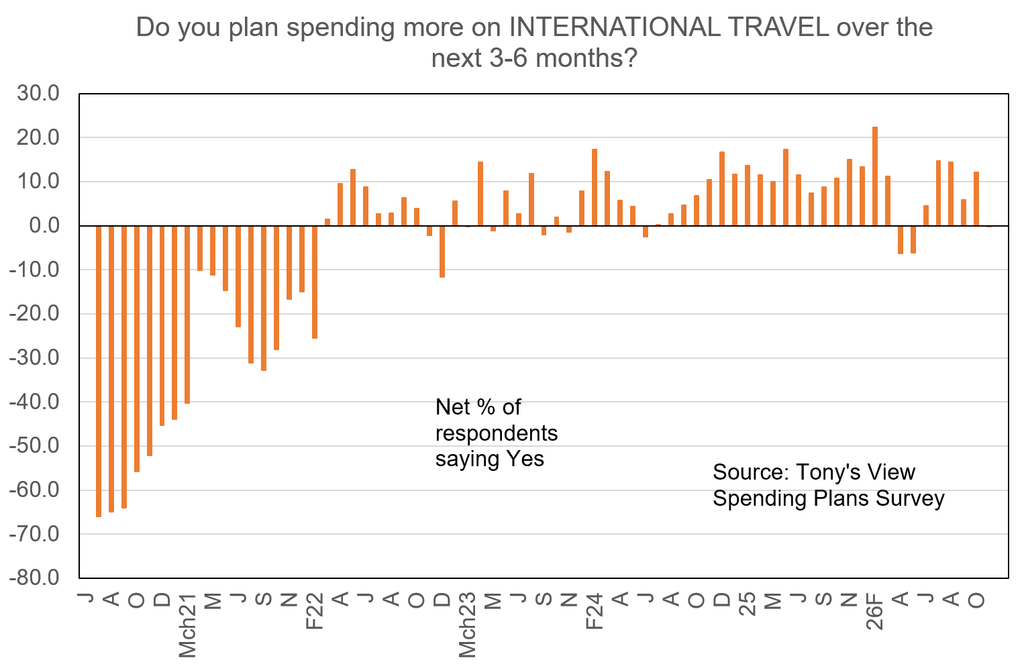
The weakness in overseas travel plans is quite sudden and not seasonal and may reflect recent airfare rises, realisation of how weak the Kiwi dollar is, or just concerns about riots and such like overseas. But this could be a statistical blip so I will wait to see next month’s result before saying we have firmly closed our wallets on travelling offshore.
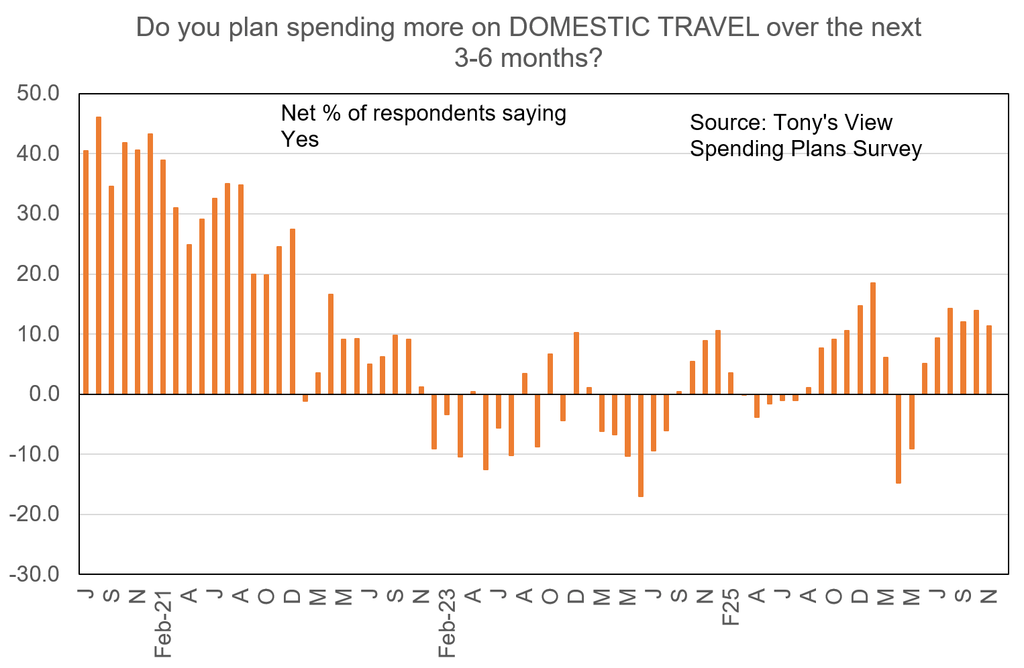
Domestic travel plans are still okay at a net 11% positive and 9% above average.
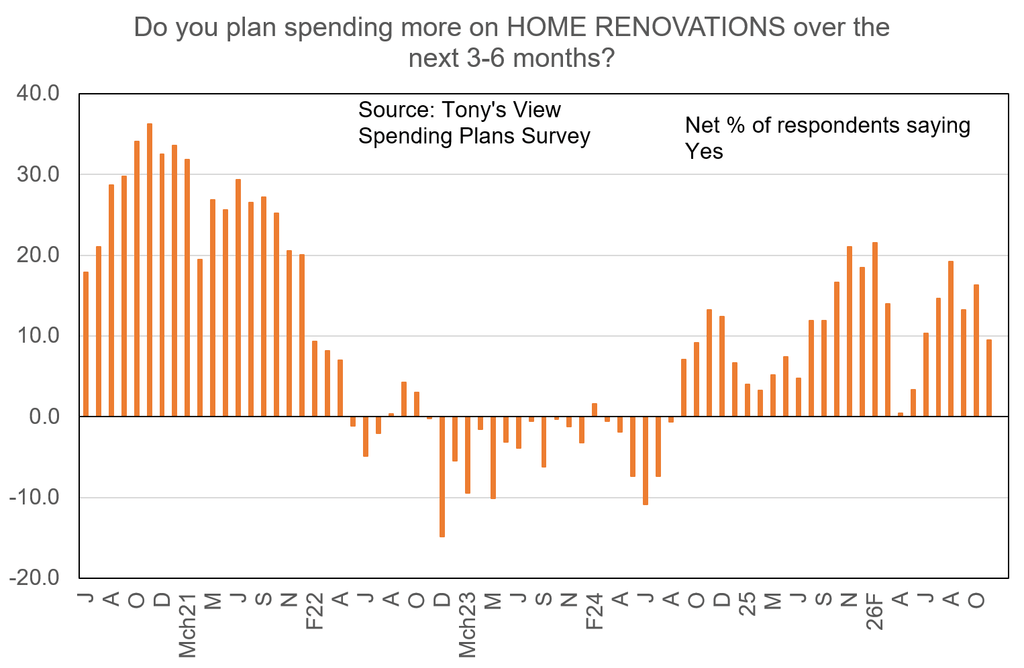
Plans to spend on Home Renovations are also okay at 10% positive and 6% above average.
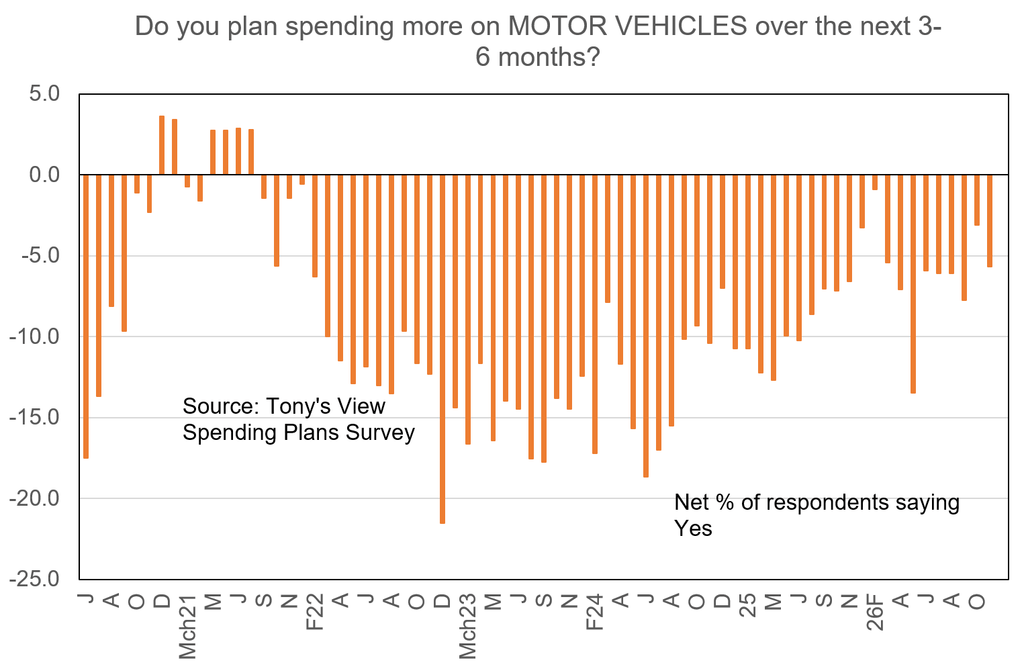
Things have deteriorated a little bit for Motor Vehicles but not enough to yet seriously conclude the improving trend has ended.
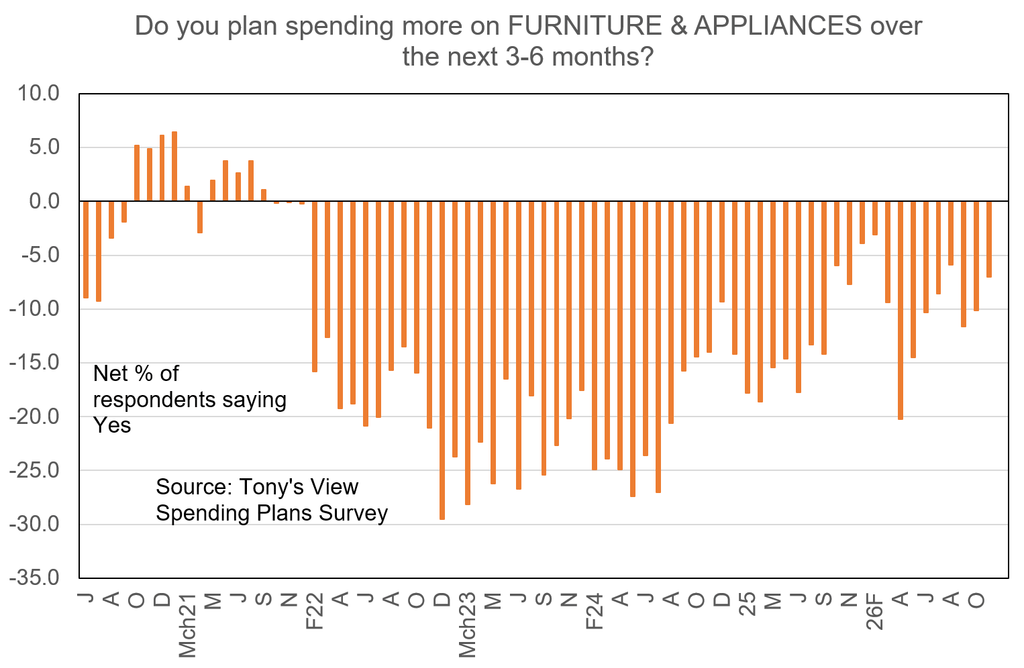
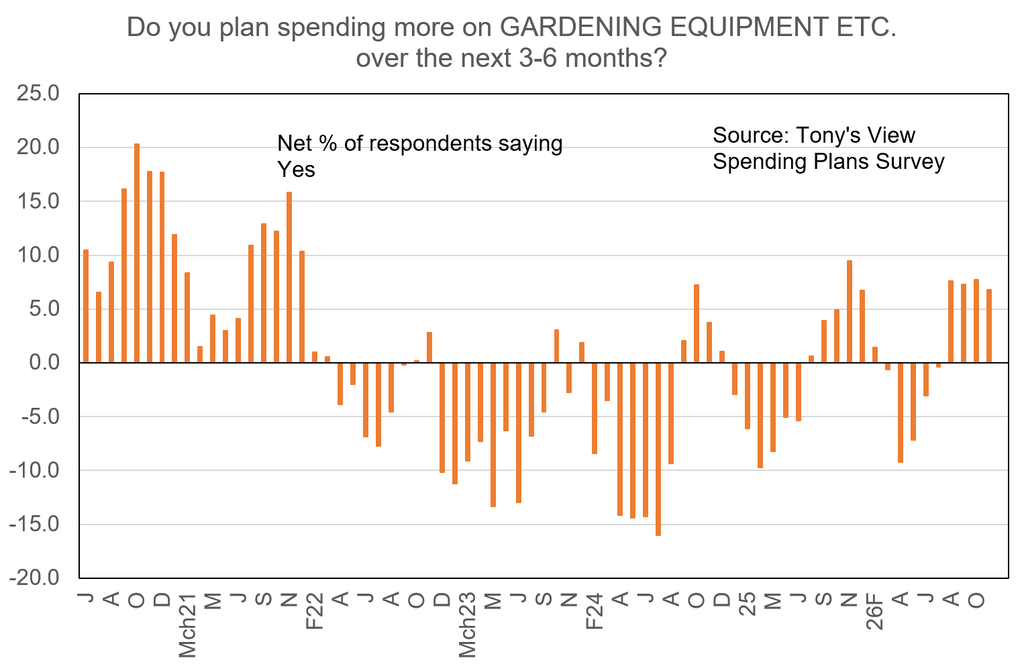
Plans for spending on Furniture and Appliances continue to improve and the approaching summer is encouraging people to think about their gardens.
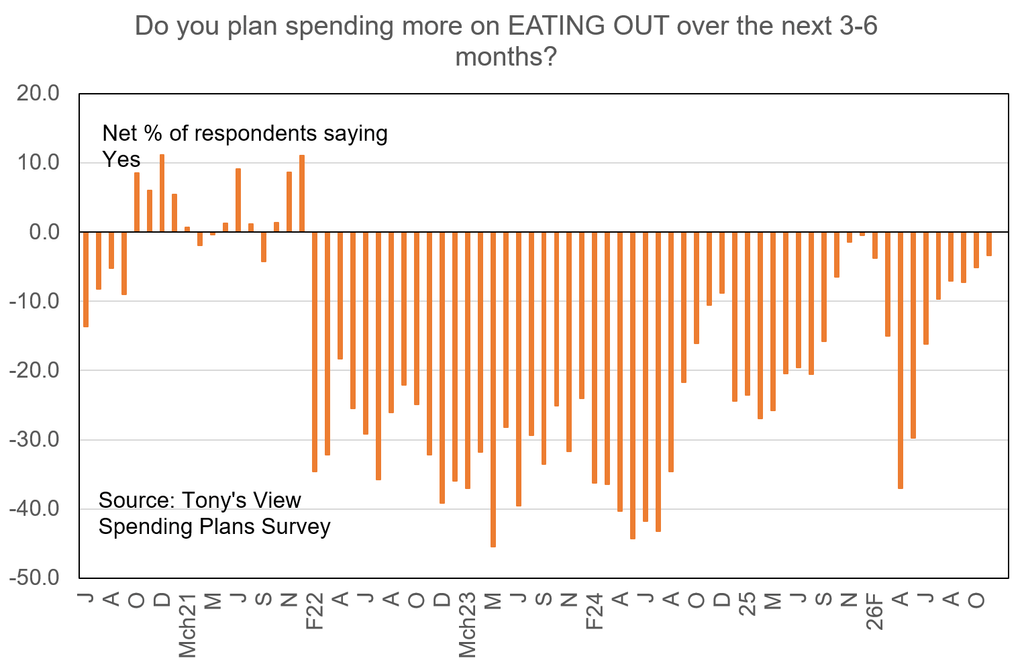
Plans for Eating Out have almost turned positive with a well above average reading (-3% versus average of -25%).
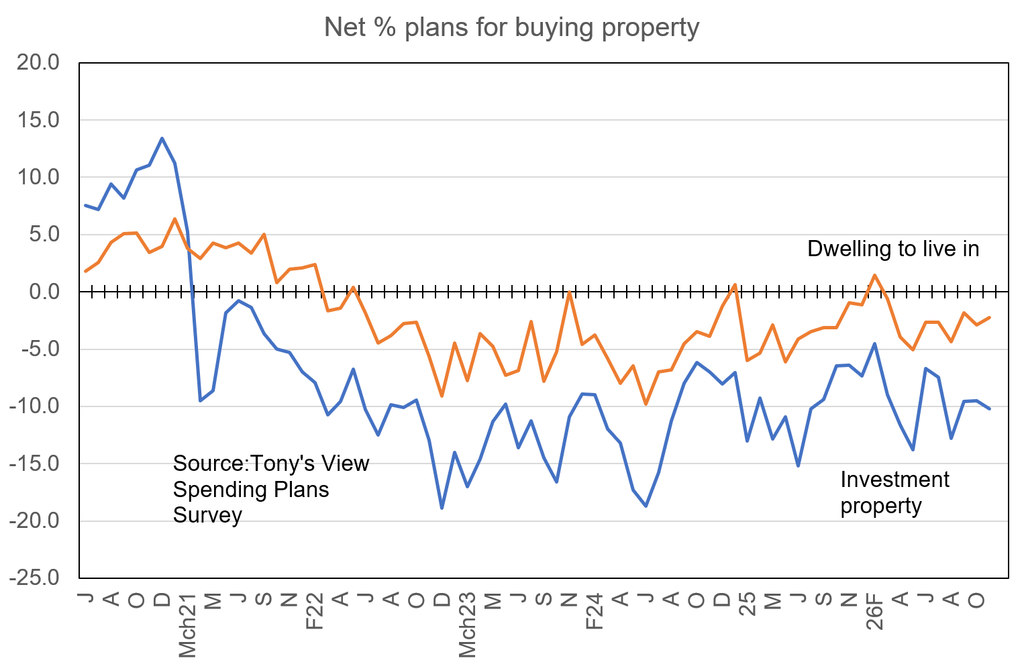
The two measures for property buying are as weak as ever. Note though the glacially slow improving trend for buying a house to live in.
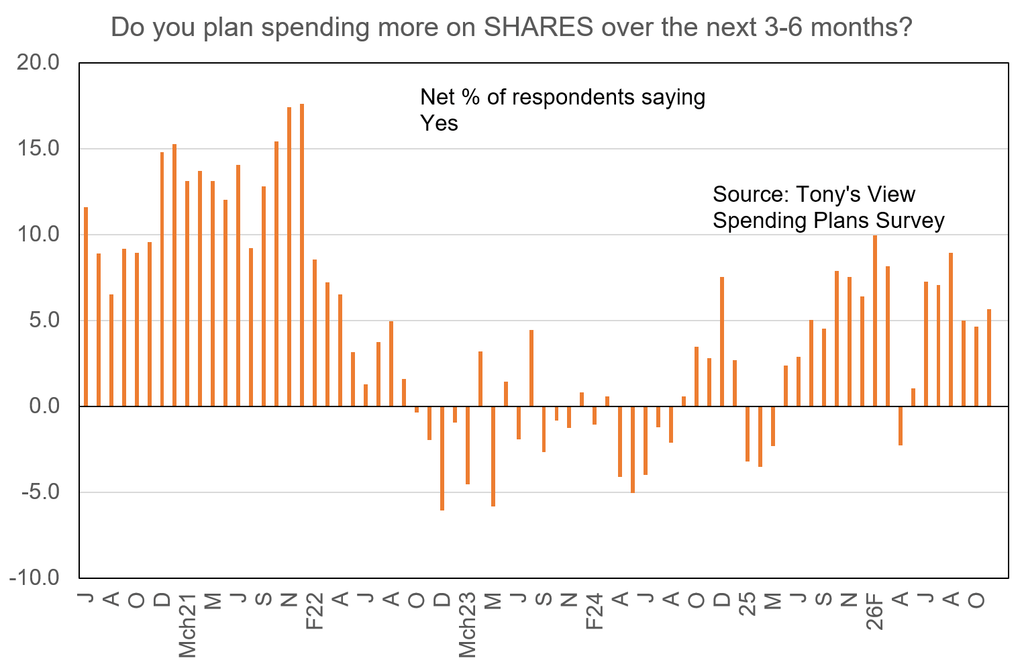
But people remain interested in shares.
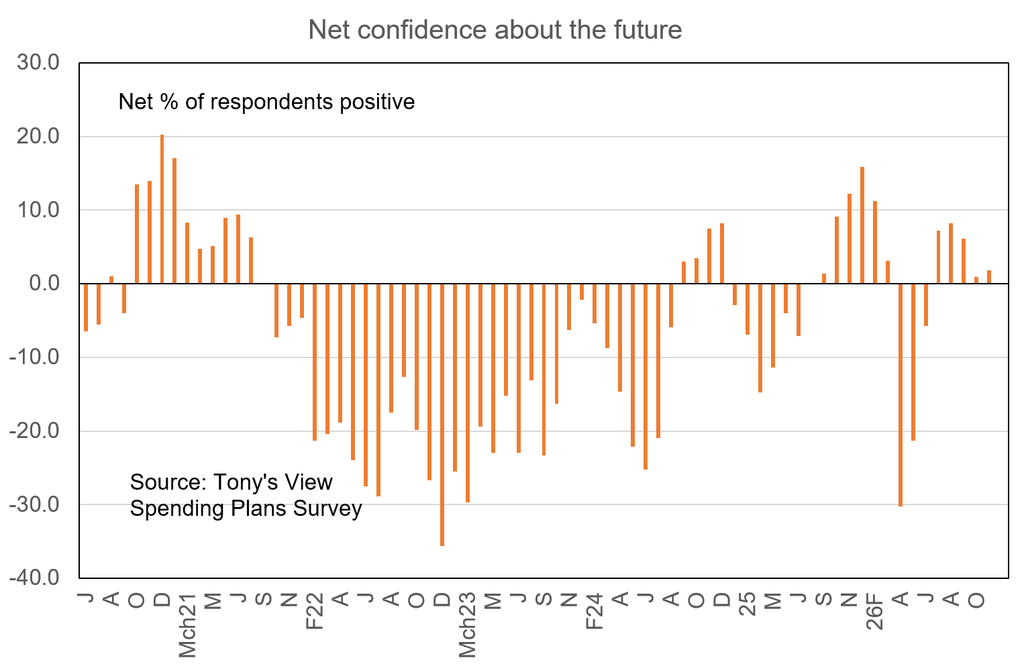
Constraining the willingness of people to spend is near net zero confidence in what the future holds.
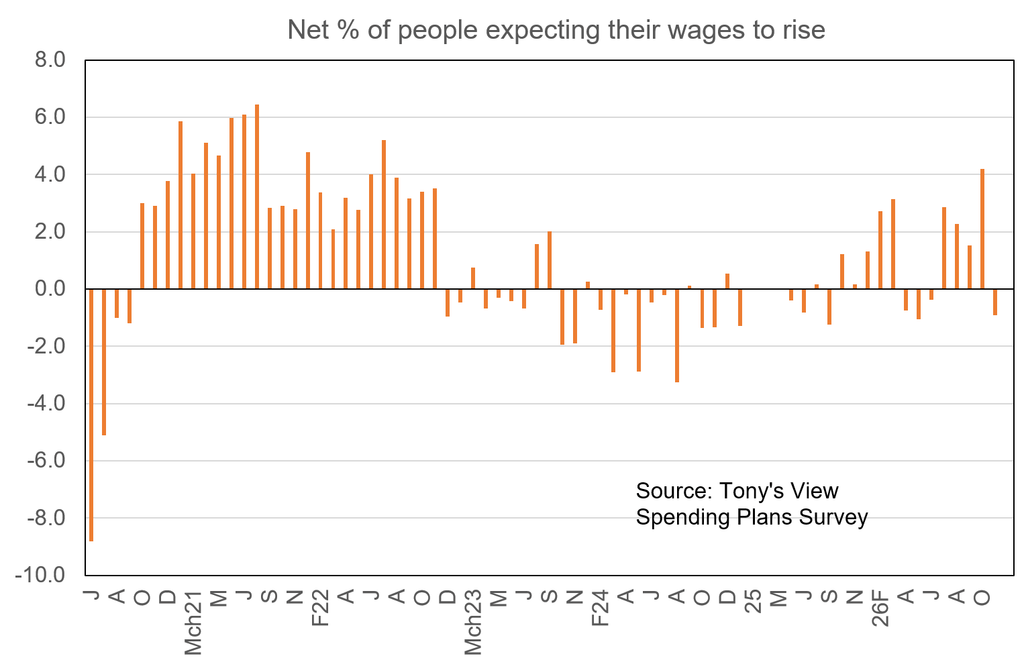
Wage growth expectations have just taken a shift down, perhaps because of the recent reporting of a rise in the unemployment rate to 5.7%.
In fact, this is where we get to the nub of things. The net proportion of people having concerns about their employment has jumped to -2.7% from -0.7% last month.
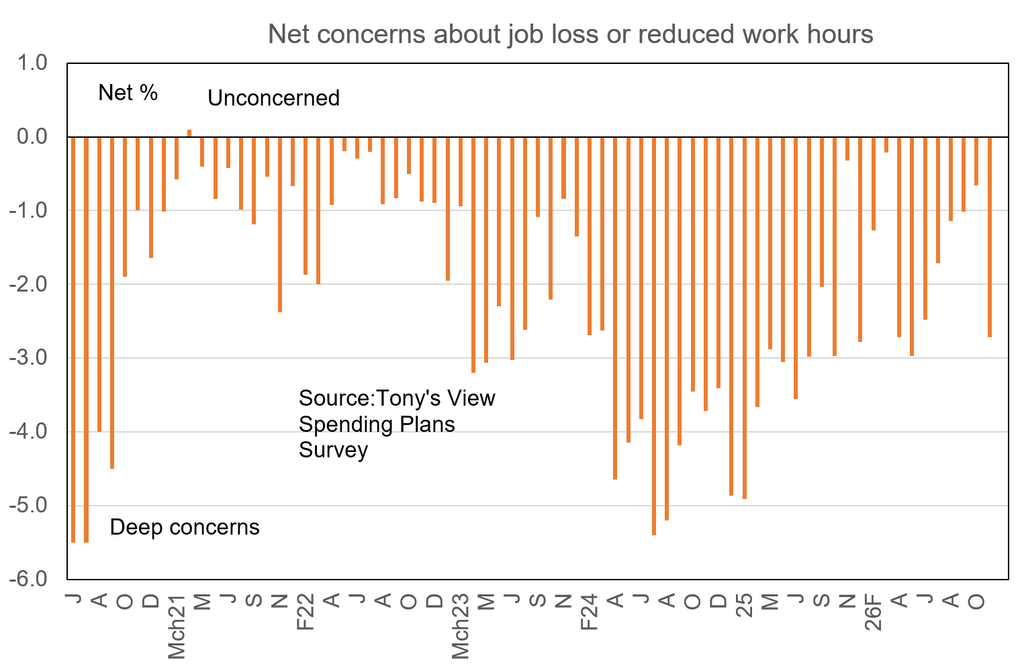
It would not be reasonable to expect and decent strength in either house prices or retail spending generally until labour market confidence notably and sustainably improves.
If I were a borrower, what would I do?
There was a little bit of excitement on Tuesday when one bank cut its one year fixed mortgage rate to 4.99%. But some other lenders were already there so this was really just a response by the lender to probable loss of market share in the term most people are highly favouring for fixing at the moment.
The underlying drift in NZ borrowing costs is upward, but we will remain subject to fluctuations coming from our economic data, the actions or inactions and comments of our central bankers, and developments in the US rates market in particular.
This week the one year swap rate at which NZ banks borrow fixed to end fixed to you and I for one year has ended near 3.54% from 3.46% last week and 3.68% a month ago. The three year rate is near 3.87% from 3.78% last week and 4.2% a month ago.
Is there scope for this sometimes popular rate to be cut? Not really. Margins are still below average and hardly anyone is looking to fix three years currently anyway so banks will likely continue to concentrate their efforts in the 1-2 year area.
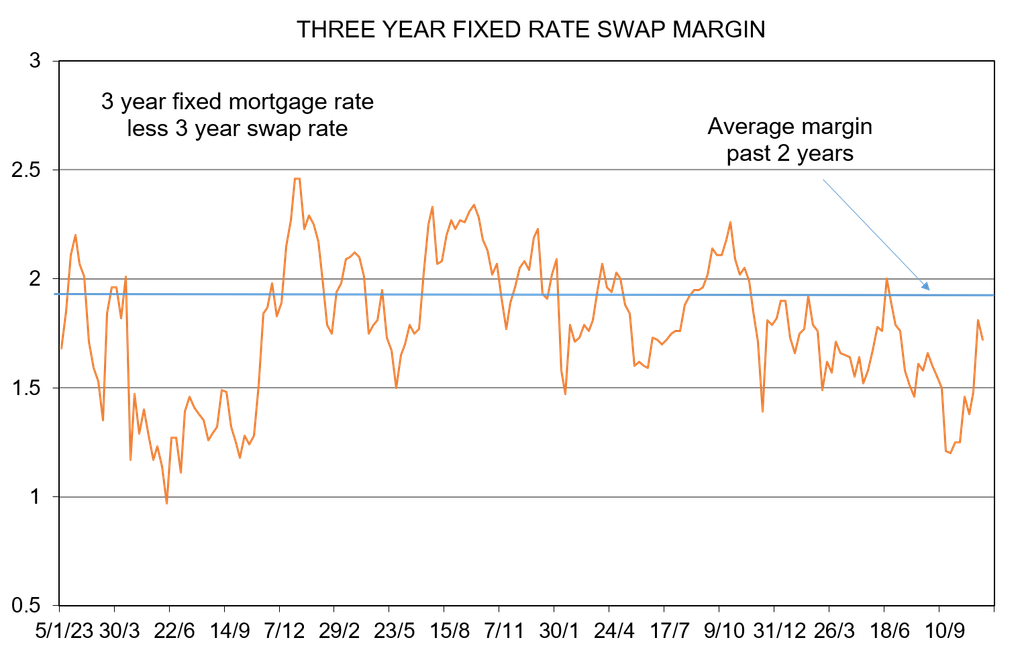
If I were borrowing at the moment, I would fix for two years but give thought to fixing for three years if I were offered a rate better than the 5.59% now commonly charged.
Nothing I write here or anywhere else in this publication is intended to be personal advice. You should discuss your financing options with a professional.